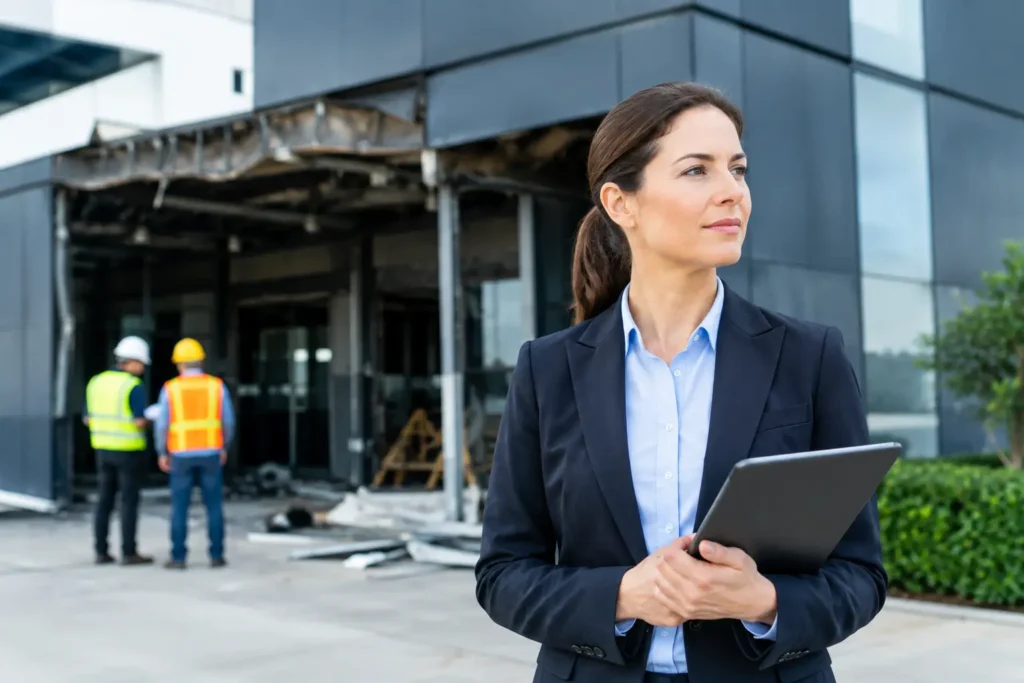
A burst pipe above a finished office, a kitchen fire in a rental home, or storm damage that exposes a roof can interrupt far more than the building itself. Business continuity after property damage is about protecting people, limiting the physical loss, preserving income, and making sound decisions before a temporary problem becomes a long closure.
For a business owner or property manager, the first few hours set the direction of the entire recovery. Water spreads through flooring and wall cavities. Smoke residue travels through HVAC pathways. A roof opening can turn the next rainfall into a second loss. Fast, documented action gives you more control over the property, the insurance claim, and the timeline to reopen.
What Business Continuity After Property Damage Really Requires
Continuity is not simply reopening the doors as soon as the visible mess is gone. A space can look dry while moisture remains behind baseboards or inside wall assemblies. It can smell acceptable while smoke residue continues to affect surfaces, inventory, or air quality. Reopening too early may expose employees, tenants, customers, and the business itself to avoidable risk.
The goal is to keep critical functions moving while restoring the property correctly. That may mean relocating staff, operating from a temporary site, creating a safe access route for tenants, protecting unaffected inventory, or shifting customer communications until repairs are complete. The right approach depends on the type of property, the source of damage, and what functions must continue without interruption.
A retail shop may need a fast, safe path to reopen its sales floor. A medical or professional office may need to protect records, equipment, and privacy. A multifamily property owner may need to stabilize units quickly while keeping residents informed. There is no single recovery timeline, but every recovery needs clear priorities.
The First 24 Hours: Stabilize Before You Strategize
The immediate priority is life safety. Keep people away from standing water near electrical sources, unstable ceilings, sewage contamination, smoke-affected areas, and broken glass. If the damage involves fire, gas, electrical hazards, or structural instability, wait for the appropriate authorities or qualified professionals to confirm the area is safe to enter.
Once the area is safe, stop the source when possible. Shut off the main water supply after a burst pipe, cover a roof opening to prevent additional rain intrusion, or secure broken windows and doors after a storm or fire. This is not cosmetic work. It is loss control.
Then document the conditions before moving or discarding damaged materials. Take wide photos of every affected room and close-ups of damaged contents, building materials, and likely points of origin. Record the date and time, note what happened, and keep invoices for emergency services, temporary relocation, equipment rental, and protective measures. Good documentation supports insurance coordination and reduces disputes about what was damaged.
For commercial properties, notify the people who need to make operational decisions: ownership, facilities leadership, the insurer, tenants, key employees, and any critical vendors. Give confirmed facts, not guesses. A short update explaining what happened, what areas are unavailable, and when the next update will be provided is more useful than silence or speculation.
Stop Secondary Damage With Professional Mitigation
Property damage rarely stays contained without immediate mitigation. Clean water can become contaminated when it sits. Saturated drywall can lose structural integrity. Moisture trapped beneath flooring can lead to mold growth and lingering odors. Smoke and soot can corrode electronics, stain porous materials, and spread beyond the original fire area.
Professional mitigation begins with inspection and moisture mapping, not with placing a few fans in the room. Certified technicians use moisture meters and thermal imaging to identify water that has traveled into hidden areas. They extract water, remove unsalvageable materials when necessary, set commercial drying equipment, and monitor the drying process until materials reach appropriate levels.
That process may feel disruptive, especially when equipment is running or portions of walls and flooring must be removed. But selective demolition is often the safer, less expensive decision when materials cannot dry properly. The trade-off is short-term inconvenience versus the risk of concealed moisture, mold, failed finishes, and a longer business interruption later.
Sewage backups and other contaminated water losses require additional care. These events are not standard cleanup jobs. Contaminated materials may need to be removed, affected surfaces disinfected, and the area verified for safe rebuilding. Attempting to save every material can create a health concern and complicate the claim.
Keep Operations Moving While the Building Is Restored
A continuity plan needs an operational side and a property side. While the restoration team manages mitigation, designate one person to coordinate internal decisions and communication. This person should know who has authority to approve emergency work, who speaks with the insurer, and how employees, tenants, or customers will receive updates.
Identify the functions that cannot wait. That may include phone coverage, payroll, client communication, deliveries, access to records, security, or tenant housing. Some businesses can work remotely for a few days. Others need temporary workspace, alternate storage, or limited operations in an unaffected portion of the building.
Protect records and equipment early. Move unaffected inventory away from wet or smoke-affected areas when it can be done safely. Do not power up electronics exposed to water or heavy soot until they have been evaluated. For digital records, confirm backups are accessible from another location. For paper files, ask a restoration professional about drying and content handling before assuming they are a total loss.
Clear communication protects revenue and trust. Customers are generally understanding when they receive timely, practical information. Let them know whether you are temporarily closed, operating with modified hours, taking appointments elsewhere, or continuing services remotely. For rental properties, give residents realistic updates about access, safety, and next steps rather than promising a finish date before the scope is known.
Build the Claim File as Work Happens
Insurance claims move more smoothly when the emergency work, documentation, and repair scope are connected. Keep a single record of photos, reports, invoices, emails, and approvals. Ask for detailed mitigation documentation, including moisture readings, affected materials, equipment logs, and a clear explanation of why removal or cleaning was necessary.
Do not delay emergency mitigation while waiting for every insurance question to be answered. Most policies require reasonable steps to prevent additional damage. At the same time, avoid authorizing broad reconstruction work without understanding the scope, your deductible, and the approval process.
It also helps to separate emergency stabilization from design choices. Returning the property to its pre-loss condition is one conversation. Choosing upgraded flooring, a redesigned kitchen, improved lighting, or a different layout is another. Upgrades can be worthwhile during reconstruction, but they may involve costs outside the covered loss. A transparent contractor will help distinguish covered repair work from elective improvements.
Choose One Recovery Partner, Not a Chain of Handoffs
The handoff between emergency cleanup and reconstruction is where many projects lose time. One company extracts water, another writes the repair scope, a third performs the build-out, and the property owner is left coordinating schedules, invoices, and conflicting opinions.
A one-stop restoration and reconstruction partner reduces that burden. The same team can document the initial loss, manage drying and cleanup, coordinate with the carrier, and move directly into repairs once the property is ready. That continuity matters because the people rebuilding the space understand what was removed, what was saved, and what the insurer has approved.
For Metro Atlanta property owners, Elevated Operations brings emergency mitigation, insurance-ready documentation, and reconstruction under one accountable relationship. That means less time managing contractors and more attention on reopening, residents, customers, and daily operations.
Turn This Loss Into a Better Continuity Plan
After the immediate crisis is controlled, document what made recovery harder than it needed to be. Maybe staff did not know where the water shutoff was located. Maybe vendor contacts were scattered across personal phones. Maybe there was no current inventory list or no designated person authorized to approve emergency work.
Create a short, usable property-loss plan with emergency contacts, utility shutoff locations, insurance policy details, a list of critical vendors, photo documentation of key rooms and equipment, and communication templates for employees or tenants. Review it after renovations, staffing changes, or a new lease.
The most useful next step is simple: before the next incident, decide who you will call, who can approve the work, and how you will keep your operation moving. When damage happens, that preparation gives you the time and clarity to protect the property instead of reacting to the chaos.